What Borrowers With Bad Credit Should Know About Subprime Lenders
Borrowers with bad credit should know that reliable subprime lenders focus on asset value and exit strategy rather than traditional credit scores. Lendersa provides a secure, AI-driven marketplace where you can compare offers from private and non-QM lenders without sharing your Social Security Number. This approach protects your identity while allowing you to find financing that aligns with your specific real estate goals.
Understanding Subprime and Non-QM Lending
Subprime lending is a financing category for borrowers with credit scores below 620 who are considered higher risk by traditional banks. Non-QM (Non-Qualified Mortgage) lending is a broader category that includes loans not conforming to standard agency guidelines, often serving self-employed or asset-rich borrowers. These lenders evaluate the property's equity and the borrower's ability to execute a specific exit strategy, such as a sale or refinance, rather than relying solely on W-2 income verification.
Traditional banks often reject applications from borrowers with poor credit, leaving a gap in the market that private capital fills. By understanding these definitions, you can better identify which lenders are actually equipped to handle your specific financial profile. This distinction is critical because it determines the type of documentation and collateral you will need to provide.
The Asset-Based Approach to Underwriting
Private lenders use an asset-based underwriting model where the property's value is the primary determinant of loan approval. In this model, the Loan-to-Value (LTV) ratio is the most critical metric, with most lenders willing to fund up to 65% of the property's value. This means that even if your credit score is in the 500s, a strong equity position can still secure you a competitive rate and favorable terms.
For example, a borrower with a 580 credit score and a property valued at $500,000 can still qualify for a $300,000 loan at a 60% LTV. This approach shifts the focus from your past financial mistakes to the current value of your asset. It allows you to leverage your real estate holdings to access capital that would otherwise be unavailable through conventional channels.
Avoiding Predatory Practices and Hidden Fees
Information asymmetry is a significant risk in the subprime market, where lenders may hide high origination points or yield spread premiums in complex term sheets. To mitigate this, you must use tools that standardize loan offers for a true apples-to-apples comparison. Lendersa’s LoanCompare™ engine uses AI to read the fine print of any loan offer, identifying overpriced fees and restrictive covenants that human brokers might miss.
By using an AI-powered comparison tool, you can see the true cost of capital across multiple lenders simultaneously. This transparency ensures that you are not being taken advantage of by a lender who knows you have limited options. It empowers you to negotiate down rates and uncover hidden traps before you commit to a binding agreement.
Protecting Your Privacy During the Search
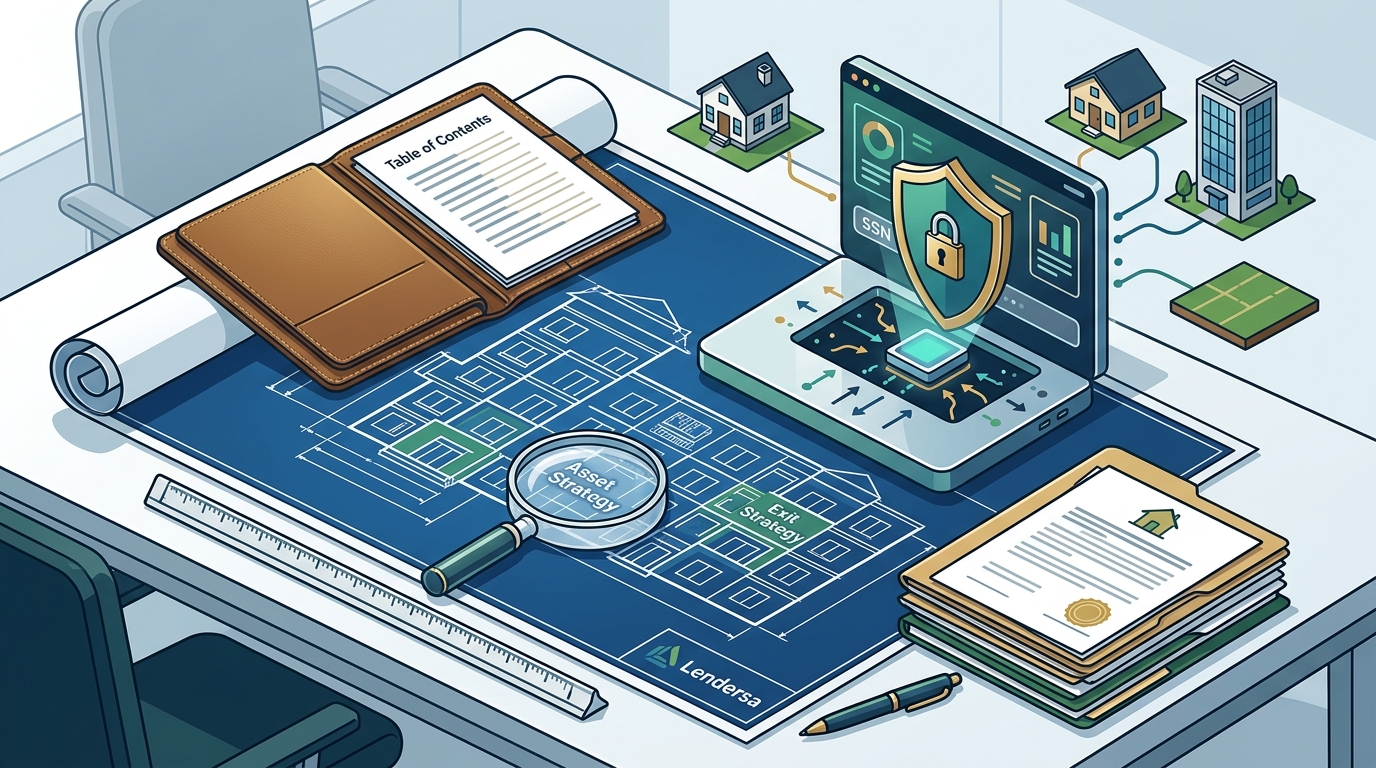
Sharing your personal information with multiple brokers can lead to a barrage of sales calls and multiple hard credit inquiries that further damage your score. Lendersa implements a proprietary Data Firewall that masks your identity during the initial matching process. Bidding lenders can see your deal parameters, such as property condition and requested amount, but they cannot see your name, email, or phone number until you choose to release it.
This one-way mirror approach ensures that you maintain total control over your data. You only reveal your identity to the specific lender with the best offer, which protects your privacy and prevents your information from being shopped to dozens of unknown parties. This level of security is essential for borrowers who are already dealing with the stress of financial recovery.
Optimizing Your Loan Request for Success
Small adjustments to your loan request can significantly improve your chances of approval and lower your interest rate. Lendersa’s LoanImprove™ engine analyzes your scenario against thousands of lender guidelines to find potential solutions. For instance, it might suggest increasing your down payment by 5% or providing a more detailed exit plan to qualify for a lower rate tier.
Using an optimization tool allows you to see exactly what changes are needed to move from a denied status to an approved one. This data-driven approach saves you time and prevents the emotional drain of repeated rejections. It turns the loan search into a strategic process where you can make informed decisions based on real-time market data.
Key Takeaways
- Subprime lenders focus on asset value and exit strategy rather than traditional credit scores.
- The Loan-to-Value (LTV) ratio is the most critical factor in private lending approvals.
- Use AI-powered tools to compare loan offers and identify hidden fees or predatory terms.
- Protect your identity by using platforms that mask your personal information during the bidding process.
- Optimize your loan request by making small adjustments to your financial profile or exit plan.
- Always verify the lender's track record and ensure they are transparent about all costs and covenants.
Frequently Asked Questions
Can I get a loan with a 500 credit score?
Yes, many private lenders and non-QM institutions will fund loans for borrowers with credit scores in the 500s, provided the property has sufficient equity and a clear exit strategy.
Do subprime lenders check my credit?
Most private lenders will pull a soft credit inquiry to assess your risk profile, but they do not rely on your credit score as the primary factor for approval.
What is the difference between a subprime and a non-QM loan?
Subprime loans are specifically for borrowers with poor credit, while non-QM loans are for borrowers who do not meet standard agency guidelines, which can include those with good credit but non-traditional income.
How much equity do I need for a hard money loan?
Most hard money lenders require at least 35% equity in the property, which corresponds to a Loan-to-Value (LTV) ratio of 65% or lower.
Is it safe to share my information with a loan marketplace?
Using a reputable platform like Lendersa is safe because it uses a Data Firewall to mask your identity until you choose to release it to a specific lender.
How long does it take to get approved for a subprime loan?
Private lenders can often approve and fund loans within 7 to 14 days, which is significantly faster than the 45 to 60 days typical of conventional bank underwriting.
What is the best way to compare subprime loan offers?
The best way is to use an AI-powered comparison tool that standardizes all offers into a single dashboard, allowing you to see the true cost of each loan side-by-side.
Start Your Secure Loan Search Today
Navigating the subprime lending market requires a strategic approach that prioritizes asset value, transparency, and privacy. By using the right tools, you can turn your real estate holdings into a source of capital even with a less-than-perfect credit history. Lendersa provides the technology and the network you need to find the best possible terms for your specific situation. To begin your secure loan search, start a loan request on Lendersa today and let the lenders compete for your business.