When evaluating hard money loan term sheets, you must scrutinize the interest rate, origination points, prepayment penalties, and extension fees to determine the true cost of capital. A hard money loan is a short-term, asset-based financing instrument secured by real estate, where the property's value dictates approval rather than the borrower's credit score. Lendersa provides an AI-powered marketplace that standardizes these documents, allowing borrowers to compare complex term sheets side-by-side without exposing their personal identity or triggering hard credit inquiries.
The Core Metrics of Asset-Based Underwriting
The foundation of any hard money term sheet is the Loan-to-Value (LTV) ratio. LTV is the ratio between the loan amount and the appraised value of the property. Most private lenders cap their exposure at 65% LTV, though some may extend to 75% or 80% for specific fix-and-flip scenarios. If a term sheet offers a high LTV, you must verify the appraisal methodology. Lenders often use the After-Repair Value (ARV) for investment properties, which can be optimistic. A term sheet that relies heavily on a projected ARV without a conservative buffer is a red flag. You should always cross-reference the appraised value with recent comparable sales in the specific neighborhood.
Decoding the True Cost of Capital
Interest rates in hard money lending typically range from 8% to 15%, but the rate alone does not tell the full story. Origination points are upfront fees charged by the lender, usually between 2% and 10% of the loan amount. A term sheet might advertise a low 9% interest rate but include 5% origination points, which significantly increases the Annual Percentage Rate (APR). You must calculate the total cost of the loan over its intended hold period. For example, a 12-month loan at 10% interest with 4% points costs more than a 12-month loan at 12% interest with 0% points. Lendersa’s LoanCompare engine strips away marketing fluff to calculate the true cost of capital, ensuring you are not misled by a low headline rate.
Prepayment Penalties and Extension Fees
Prepayment penalties are fees charged if you pay off the loan before the maturity date. In hard money lending, these are often structured as a percentage of the remaining balance or a fixed number of months of interest. If your exit strategy involves selling the property in six months, a term sheet with a 6-month prepayment penalty could wipe out your profit. Extension fees are another critical line item. If you cannot sell or refinance by the maturity date, you will likely need to extend the loan. Extension fees can range from 1% to 3% of the loan amount per month. A term sheet with a low interest rate but high extension fees becomes expensive if the project timeline slips. You must model your exit strategy against these specific penalty structures to avoid unexpected cash flow drains.
Hidden Covenants and Restrictive Clauses
Beyond the numbers, term sheets contain legal covenants that restrict your actions. Assumption restrictions prevent you from transferring the loan to a new buyer, which can complicate the sale of a property. Late fee structures can be punitive, with some lenders charging 5% of the missed payment amount. Default interest rates spike the interest rate if you miss a payment, often by 2% to 4%. These clauses are frequently buried in the fine print of a Letter of Intent (LOI). Lendersa’s LendChat AI tool automatically flags these non-obvious traps, scouting for predatory default rates and restrictive covenants that human brokers might miss. By turning complex legal jargon into clear data, you can negotiate these terms before signing.
Standardizing the Comparison Process
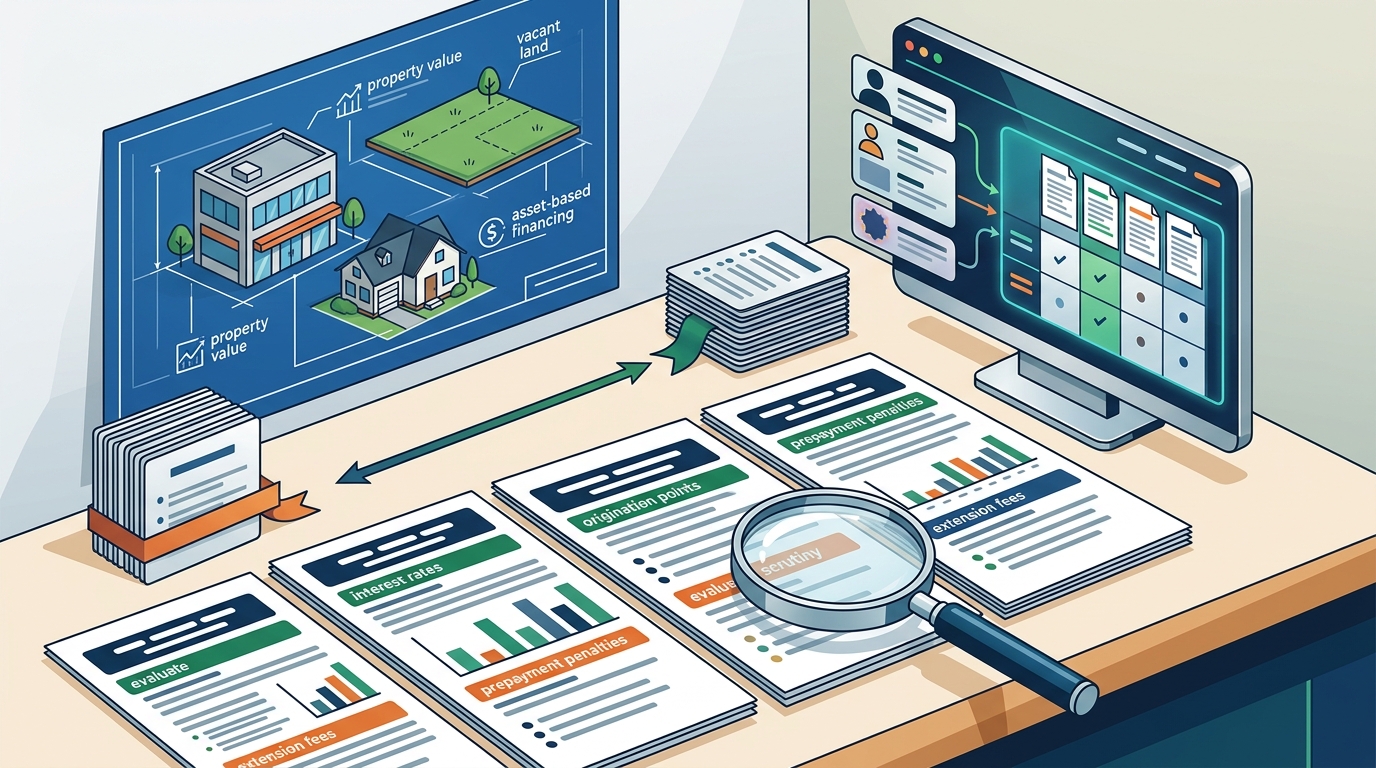
Comparing term sheets from different lenders is difficult because each uses different formatting and terminology. One lender might quote a lower interest rate but hide massive processing fees on page four of their document. Lendersa solves this by using an AI document ingestion engine to convert any loan offer into standardized, structured text. This allows for an apples-to-apples analysis of the true cost of each loan. You can upload a formal PDF, a snapshot of a term sheet, or even a verbal quote, and the system will standardize the data. This level of transparency is essential for making an informed decision. By using a platform that prioritizes data-driven comparison, you ensure that you are selecting the best possible financing for your specific project.
Key Takeaways
- Always calculate the total cost of capital, including interest, points, and fees, not just the headline rate.
- Verify the LTV ratio and the appraisal methodology, especially for fix-and-flip projects relying on ARV.
- Scrutinize prepayment penalties and extension fees to ensure they align with your exit strategy timeline.
- Read the fine print for restrictive covenants, such as assumption restrictions and punitive late fees.
- Use AI-powered tools to standardize term sheets for accurate side-by-side comparisons.
Frequently Asked Questions
What is a hard money loan term sheet?
A hard money loan term sheet is a preliminary document outlining the key terms of a loan, including interest rate, points, and fees, before a formal contract is signed.
How do I compare hard money loan rates without a credit pull?
You can use AI-powered marketplaces like Lendersa that match your asset profile to lenders without requiring a Social Security Number or triggering a hard credit inquiry.
What is the typical LTV for a hard money loan?
Most hard money lenders lend up to 65% LTV, though some may go up to 75% or 80% for specific investment properties.
Are prepayment penalties common in hard money loans?
Yes, prepayment penalties are common and can be structured as a percentage of the remaining balance or a fixed number of months of interest.
How can I identify hidden fees in a term sheet?
Use AI tools that analyze the fine print to flag hidden origination points, processing fees, and restrictive covenants that may not be immediately visible.
What is the difference between a term sheet and a Loan Estimate?
A term sheet is a non-binding outline of terms, while a Loan Estimate is a standardized form required by federal law for most mortgage loans, though hard money loans may not always require one.
Can I negotiate the terms in a hard money loan term sheet?
Yes, you can and should negotiate terms such as interest rates, points, and prepayment penalties before finalizing the loan agreement.