How Modern Loan Marketplaces Connect Borrowers to Multiple Lenders
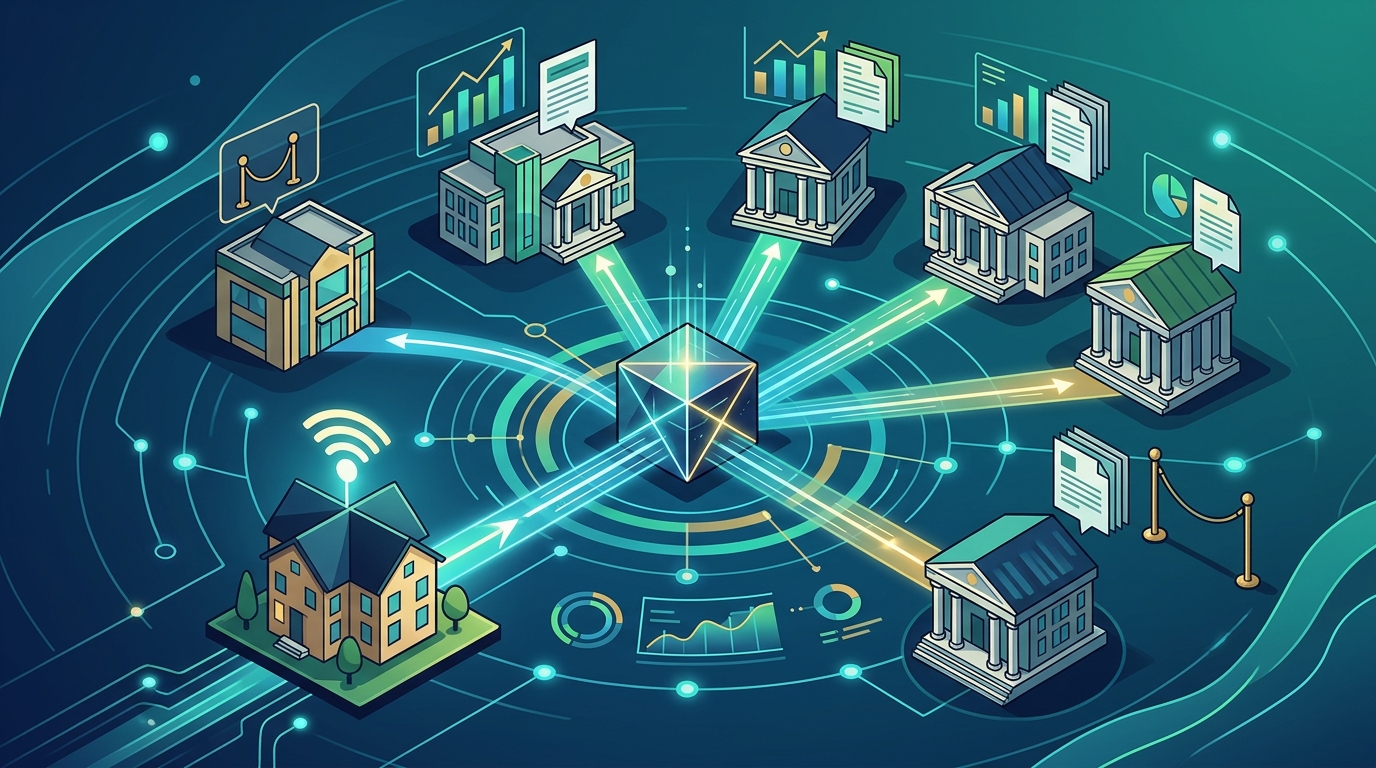
Modern loan marketplaces connect borrowers with multiple lenders simultaneously by using algorithmic matching engines to broadcast a single loan request to a network of pre-qualified financial institutions. This digital infrastructure replaces the traditional, sequential process of contacting banks one by one. By aggregating diverse funding sources, these platforms allow borrowers to compare competing offers in real time. Lendersa exemplifies this model by leveraging artificial intelligence to align specific loan scenarios with compatible capital providers instantly.
The Algorithmic Matching Engine
At the core of any modern lending marketplace is a sophisticated matching algorithm. This system is not a simple directory; it is a dynamic engine that evaluates dozens of underwriting criteria. When a borrower submits a request, the platform analyzes data points such as loan-to-value ratios, credit scores, and property types. The algorithm then filters the lender network to identify only those institutions whose specific risk appetites align with the borrower's profile. according to Online loan marketplaces
This precision is critical for efficiency. Traditional methods often result in borrowers receiving rejections from lenders who simply do not fund that specific asset class. By pre-filtering the network, the marketplace ensures that every lender who receives the request has a high probability of being able to fund the deal. This reduces the administrative burden on both sides and accelerates the path to a term sheet. according to The Fed Private
Simultaneous Broadcasting and Competition
The defining feature of a modern marketplace is the ability to broadcast a single application to multiple lenders at once. This mechanism transforms the lending process from a monologue into a competitive auction. When several lenders receive the same data simultaneously, they are incentivized to offer their most favorable rates and terms to win the business. This competition directly benefits the borrower by driving down interest rates and reducing origination fees. according to Student Loan Refinance
For example, a commercial real estate investor seeking a bridge loan can submit one request to a marketplace. Within minutes, that request is distributed to dozens of private money lenders and institutional funds. The borrower then receives multiple competing offers, allowing them to select the best fit without the time-consuming process of individual outreach. This simultaneous approach is the primary driver of the cost savings observed in digital lending. according to How loan descriptions
Standardized Data and Underwriting
One of the biggest friction points in traditional lending is the lack of standardized data. Different banks and private lenders often require different document formats and data points. Modern marketplaces solve this by enforcing a standardized data protocol. The platform collects all necessary financial information, property details, and business metrics in a single, structured format. This ensures that every lender in the network receives the same complete package of information.
Standardization also allows for faster underwriting. Because the data is pre-validated and structured, lenders can run their internal risk models more quickly. This reduces the back-and-forth communication that typically slows down the approval process. For borrowers, this means a faster time to funding, which is often the most critical factor in real estate and business acquisitions.
The Role of Artificial Intelligence
Artificial intelligence has become the backbone of modern loan marketplaces. AI systems can analyze unstructured data, such as business plans or property descriptions, to extract relevant underwriting signals. This capability allows the platform to match borrowers with lenders who might not have been identified by a simple rule-based system. AI also enables the platform to provide real-time guidance to borrowers, helping them optimize their requests for better outcomes.
Furthermore, AI can predict which lenders are most likely to approve a specific loan scenario. By analyzing historical data on lender behavior, the platform can rank the probability of approval for each lender in the network. This predictive capability helps borrowers manage their expectations and focus their negotiations on the most viable options. The integration of AI transforms the marketplace from a passive directory into an active, intelligent advisor.
Key Takeaways
- Algorithmic matching ensures that loan requests are only sent to lenders with compatible risk profiles.
- Simultaneous broadcasting creates a competitive environment that drives down rates and fees.
- Standardized data protocols reduce friction and accelerate the underwriting process.
- Artificial intelligence enhances matching precision and provides predictive insights on approval likelihood.
- Marketplaces empower borrowers by shifting the power dynamic from lenders to consumers.
- Digital platforms provide transparency and speed that traditional brick-and-mortar banks cannot match.
Frequently Asked Questions
Do loan marketplaces charge borrowers for their services?
Most modern loan marketplaces, including Lendersa, are free for borrowers to use. The platform is typically monetized through success fees paid by lenders when a loan closes. This model aligns the incentives of the marketplace with the success of the borrower's transaction.
How many lenders can I connect with at once?
The number of lenders a borrower can connect with depends on the specific marketplace and the loan scenario. Some platforms may connect a borrower with dozens of lenders, while others may focus on a smaller, more curated network. The key is the quality of the match, not just the quantity of lenders.
Is my personal information safe on a loan marketplace?
Reputable loan marketplaces use robust security measures to protect borrower data. This includes encryption, secure data storage, and strict privacy policies. Borrowers should always review the platform's privacy policy to understand how their data is handled and shared.
Can I use a marketplace for both residential and commercial loans?
Yes, many modern marketplaces support a wide range of loan types, including residential mortgages, commercial real estate loans, and small business financing. The platform's matching engine is designed to handle the diverse underwriting criteria associated with each loan type.
What happens if no lenders respond to my request?
How does a marketplace differ from a traditional mortgage broker?
A traditional mortgage broker typically works with a limited panel of lenders and may have a conflict of interest in steering borrowers toward specific products. A loan marketplace, on the other hand, connects borrowers with a wide network of lenders and operates on a transparent, competitive model. The marketplace's goal is to facilitate the best possible outcome for the borrower through competition.